Rising oil prices threaten NYC’s construction boom
Subscribe to our free newsletter today to keep up to date with the latest construction news.
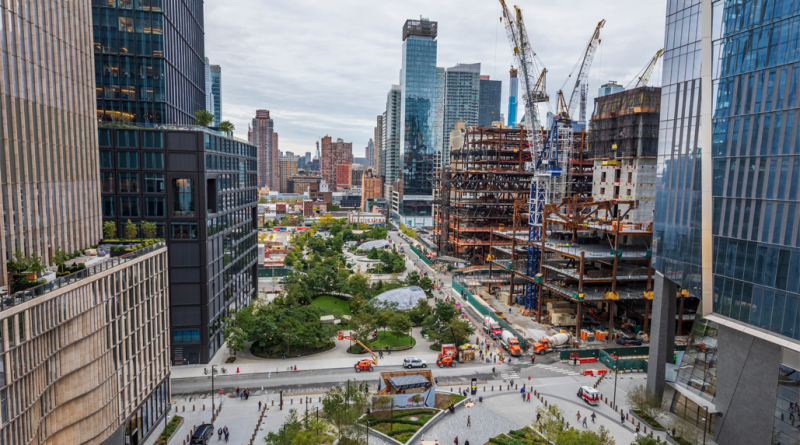
New York City’s construction pipeline remains active despite higher interest rates and shifting demand across asset classes. Large-scale residential towers, mixed-use developments and infrastructure upgrades continue to move forward, supported by long-term capital commitments and structural housing shortages. Energy markets are introducing a new variable that developers cannot control.
Oil prices sit at the center of construction economics. Their influence extends beyond fuel, shaping the cost of transporting materials, powering equipment and manufacturing key inputs. Diesel, which underpins logistics and on-site operations, has shown sharp price swings in recent months. Even modest increases translate into higher project costs when applied across long timelines and complex supply chains.
The connection becomes more direct when looking at petroleum-based materials. Asphalt pricing tends to move in near real time with crude oil, while plastics, sealants and insulation products depend on petrochemical derivatives. For a city like New York, where construction sites rely heavily on imported materials, these cost pressures are amplified by transportation and handling requirements.
Recent oil market volatility, driven by geopolitical tensions and constrained supply, has added uncertainty. Developers who previously focused on interest rates and labor availability must now account for energy exposure across every phase of a project. This shift is changing how deals are structured and how risk is distributed across stakeholders.
Cost escalation is changing project feasibility and timelines
Rising energy prices are feeding into a broader wave of construction cost inflation. Materials such as steel and aluminum have recorded double-digit increases, reflecting energy-intensive production processes and supply constraints. Asphalt and concrete costs are also climbing, driven by fuel inputs and transportation expenses.
For developers, the result is a steady erosion of project feasibility. Industry estimates suggest overall construction costs may increase between 2 percent and 6 percent under sustained oil price pressure. That range often determines whether a project clears financing thresholds or stalls before breaking ground.
Timelines are shifting. Higher fuel and material costs can lead to procurement delays, particularly when contractors attempt to time purchases or renegotiate supplier agreements. In complex developments, this can extend project schedules by 5 percent to 15 percent, creating knock-on effects for financing, leasing and revenue projections.
Contract structures are evolving in response. Fixed-price agreements, once a preferred option for cost certainty, now carry greater risk for contractors operating in a volatile input environment. Many are pushing for escalation clauses tied to fuel or material indices, transferring part of that risk back to developers. This dynamic is reshaping negotiations and adding complexity to already tight deal structures.
Lenders and investors are adjusting. Underwriting models incorporate contingencies for energy-driven cost increases, while some capital providers are taking a more cautious stance on new starts. The result is a more selective development environment, where projects with strong fundamentals and financial flexibility are more likely to proceed.
Developers and contractors adjust to uncertainty
Faced with rising costs and limited visibility, developers and contractors are rethinking how projects are planned and executed. Some are delaying starts in anticipation of more stable pricing, while others are moving ahead while building larger contingencies into budgets.
Procurement strategies are shifting toward diversification. Contractors are seeking alternative suppliers, locking in prices earlier where possible and exploring substitute materials that offer cost stability. These approaches can mitigate risk but often require trade-offs in design, quality or timelines.
Larger, well-capitalized developers are generally better positioned to absorb short-term volatility. They can leverage scale, access more flexible financing and negotiate favorable terms with suppliers. Smaller players face tighter margins and less room to adjust, increasing the likelihood of delays or cancellations.
Labor dynamics add another layer of pressure. As material costs rise, subcontractors adjust pricing to protect margins, contributing to overall cost escalation. In a market like New York, where labor costs are already among the highest in the US, this compounds the financial challenge for developers.
Activity continues, though at a more measured pace. Projects face greater scrutiny, and decision-making timelines are lengthening as stakeholders assess risk from multiple angles.
The resilience of New York City’s construction pipeline will depend on how energy markets evolve in the coming months. If oil prices stabilize, current cost pressures may ease, allowing delayed projects to move forward and restoring some confidence among developers and investors.
If volatility continues, the impact could extend beyond individual projects. A sustained period of elevated energy costs may reduce the number of new starts, particularly in segments with tighter margins such as multifamily housing. Over time, this could constrain supply and influence pricing dynamics across the real estate market.
Investor sentiment is shifting. Capital is becoming more selective, favoring projects with strong pre-leasing, conservative assumptions and experienced sponsors. Infrastructure and public sector projects may also face renewed scrutiny as budgets adjust to higher input costs.
At a broader level, the situation highlights the growing link between global energy markets and local construction activity. For NYC, a city that depends on continuous development to support economic growth, this connection introduces complexity that is unlikely to fade.
Sources:
Bisnow