Atlanta leads the US in data center construction
Subscribe to our free newsletter today to keep up to date with the latest construction news.
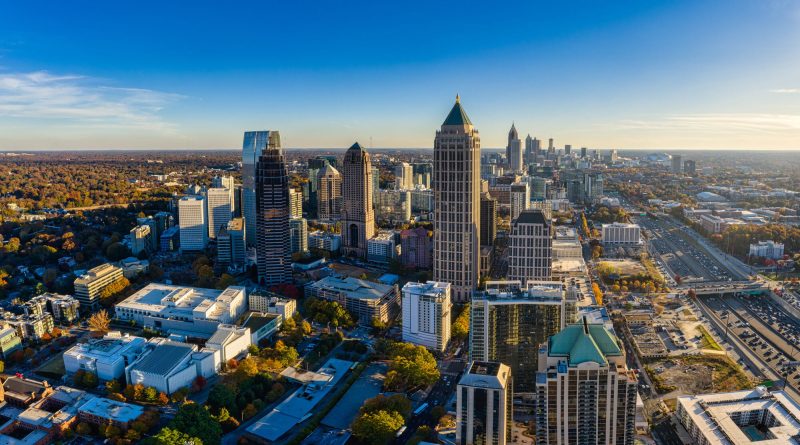
Atlanta has moved ahead of Northern Virginia as North America’s largest market for data center capacity under construction, signaling a shift in where the industry’s next wave of infrastructure is being built.
The Atlanta market had 2,882 MW of capacity under construction during the first half of 2026, according to CBRE. That was up 52.3% from a year earlier and put the market ahead of Northern Virginia for the first time.
The change does not mean Atlanta is now the region’s largest data center market overall. Northern Virginia remains far larger by existing capacity, with almost 4,500 MW of inventory compared with about 1,800 MW in Atlanta.
Construction activity, however, shows where new investment is moving.
Atlanta’s rise reflects several trends reshaping data center development across the US. Demand for computing capacity continues to grow, while developers face tighter limits on where large projects can secure enough power. Markets that can offer electricity, land and room for infrastructure expansion are becoming more important.
For construction and engineering companies, the opportunity extends beyond the data center buildings themselves. Large projects require major electrical works, substations, transmission infrastructure, cooling systems, backup power and civil engineering.
Record construction is still struggling to keep pace with demand
Data center construction across North America is already running at record levels.
CBRE reported 7,481.1 MW of capacity under construction across the eight largest North American markets during the first half of 2026. That was up 24.8% from the previous year.
Yet the increase in supply has done little to loosen the market.
Vacancy across those markets fell to a record 1.4%, even as total inventory increased by more than a third. More than 80% of the capacity under construction has already been committed to customers.
The figures suggest developers are still struggling to build fast enough to match demand.
AI workloads are one reason. Training and running large AI models can require far more computing power than many traditional enterprise applications. Large cloud providers and technology companies are therefore seeking bigger data center campuses with higher power allocations.
That has changed the scale of many projects.
Major developments were once measured in tens of megawatts. New campuses can now involve hundreds of megawatts, while some planned projects are measured at gigawatt scale.
This puts greater pressure on power grids and makes construction schedules harder to manage. A developer may have land and financing, but a project cannot move ahead without a clear route to electricity.
Preleasing also shows how tight the market has become.
When most capacity is committed before construction is finished, companies looking for more computing space have fewer immediate options. That supports continued development, but it also raises the pressure on developers to bring projects online on schedule.
Atlanta’s advantage increasingly comes down to power
Atlanta’s growth cannot be explained by real estate availability alone.
Power has become one of the main factors deciding where data centers can be built.
CBRE has reported more than 3 GW of long-term power commitments in the Atlanta market. It has also pointed to approvals that could support more than 10 GW of future data center expansion across Georgia.
That potential supply gives developers a reason to consider Atlanta at a time when established markets face grid constraints.
Northern Virginia shows the challenge.
It remains the largest existing data center market in North America and continues to record strong demand. But years of rapid development have placed pressure on local power and transmission infrastructure.
That does not remove Northern Virginia from the market. Its installed base, fiber connections and existing data center network remain major advantages.
What is changing is the number of markets considered suitable for very large new developments.
Developers are increasingly looking at where power can be delivered within a practical construction timeline. That can direct investment toward markets where utilities have more capacity to add generation, transmission or substations.
Atlanta appears to be benefiting from that shift.
Its construction lead should still be viewed with caution. Capacity under construction is not the same as completed capacity. Large developments can face delays linked to power connections, equipment supply, permitting and local planning.
Even so, the volume of construction shows where developers are committing capital today.
The construction boom will test energy and infrastructure capacity
The expansion of data centers is becoming a larger part of the industrial construction market.
Each major campus can require extensive electrical infrastructure, cooling equipment, backup generation, water systems, security, roads and telecommunications connections.
That creates demand across several parts of the construction supply chain.
Electrical contractors may need to deliver substations, switchgear and distribution systems. Mechanical contractors face growing demand for cooling infrastructure. Utilities may need to build new transmission lines or reinforce existing networks.
Equipment manufacturers are also being asked to support much larger projects.
At the same time, the scale of development creates new risks.
Power infrastructure can take years to plan and build. Large transformers and other electrical equipment can have long procurement periods. Local opposition may also increase when communities face proposals for large developments that consume substantial amounts of electricity and land.
These limits could become more important as the industry expands beyond its traditional locations.
The main question is shifting from where companies want to build data centers to where they can secure power and complete construction on a practical timeline.
Atlanta’s move to the top of the construction rankings offers one example of that change.
Northern Virginia remains the largest established market, but the next stage of US data center growth is becoming more geographically spread out. Markets that can provide large amounts of power, suitable sites and infrastructure capacity are likely to attract a greater share of new construction.
For the construction sector, data center demand is likely to remain strong. The bigger test will be whether energy and infrastructure systems can keep pace.
Source